Pet Insurance Claims: Cleaner Filings With AI Decision Tools
Pet Protection Made Simple: Your Ultimate Guide to Pet Insurance Claims and AI-Driven Decisions
Vet bills can spike fast—often right when your pet needs care most. Pet insurance can help, but only if you choose a policy with intent and set yourself up to file clean claims. Our team put together this practical guide to help you pick coverage, reduce claim delays, and use AI-style decision tools (like plan comparators, cost calculators, and policy analyzers) to cut down on guesswork—while keeping you in control of the final call.
Start with the problems pet insurance is meant to solve
Pet insurance isn’t just “coverage.” It’s a way to reduce specific pressure points that show up at the clinic and in your budget.
- Budget shock: Large, unexpected costs such as diagnostics, surgery, hospitalization, specialist care, or chronic-condition management.
- Trade-offs at the clinic: Less pressure to choose between finances and a vet’s recommended plan.
- Long-term predictability: Shifting some risk into a steady premium and a known deductible/co-insurance structure.
- Peace-of-mind planning: Knowing what typically gets reimbursed, what doesn’t, and how timing works.
Know the moving parts: premiums, deductibles, reimbursement, and limits
Most pet insurance decisions come down to a small set of variables. If you can explain these in plain language, you can compare plans much faster.
- Premium: The recurring cost to keep the policy active, often affected by your pet’s age, breed, location, and options you choose.
- Deductible: The portion you pay before reimbursement begins; it may be annual or per-incident.
- Reimbursement rate: The percentage of eligible costs covered after the deductible (for example, 70%, 80%, 90%).
- Limits: Annual, per-incident, or lifetime maximums that cap reimbursements.
- Waiting periods: Time after enrollment before certain coverages start (often different for accidents vs. illnesses).
- Exclusions and definitions: What counts as covered, what’s considered pre-existing, and what preventive care is outside the plan.
Quick decision grid for common plan choices
| Plan choice | Best when | Watch-outs |
|---|---|---|
| Higher deductible + lower premium | Comfortable covering smaller bills; protection mainly for big events | Claims start later; more out-of-pocket early in the year |
| Lower deductible + higher premium | Expect regular vet usage or prefer predictable out-of-pocket costs | Premium cost can rise over time; verify annual limits |
| Higher reimbursement rate | Want smaller co-pays after deductible for eligible claims | May come with higher premium; check if limits still constrain payouts |
| Accident-only coverage | Primary concern is injuries and emergencies | Illnesses and chronic conditions typically not covered |
| Accident + illness coverage | Want broader help for infections, cancers, allergies, chronic care | Read exclusions carefully; pre-existing rules are pivotal |
Build a claim-ready routine before anything happens
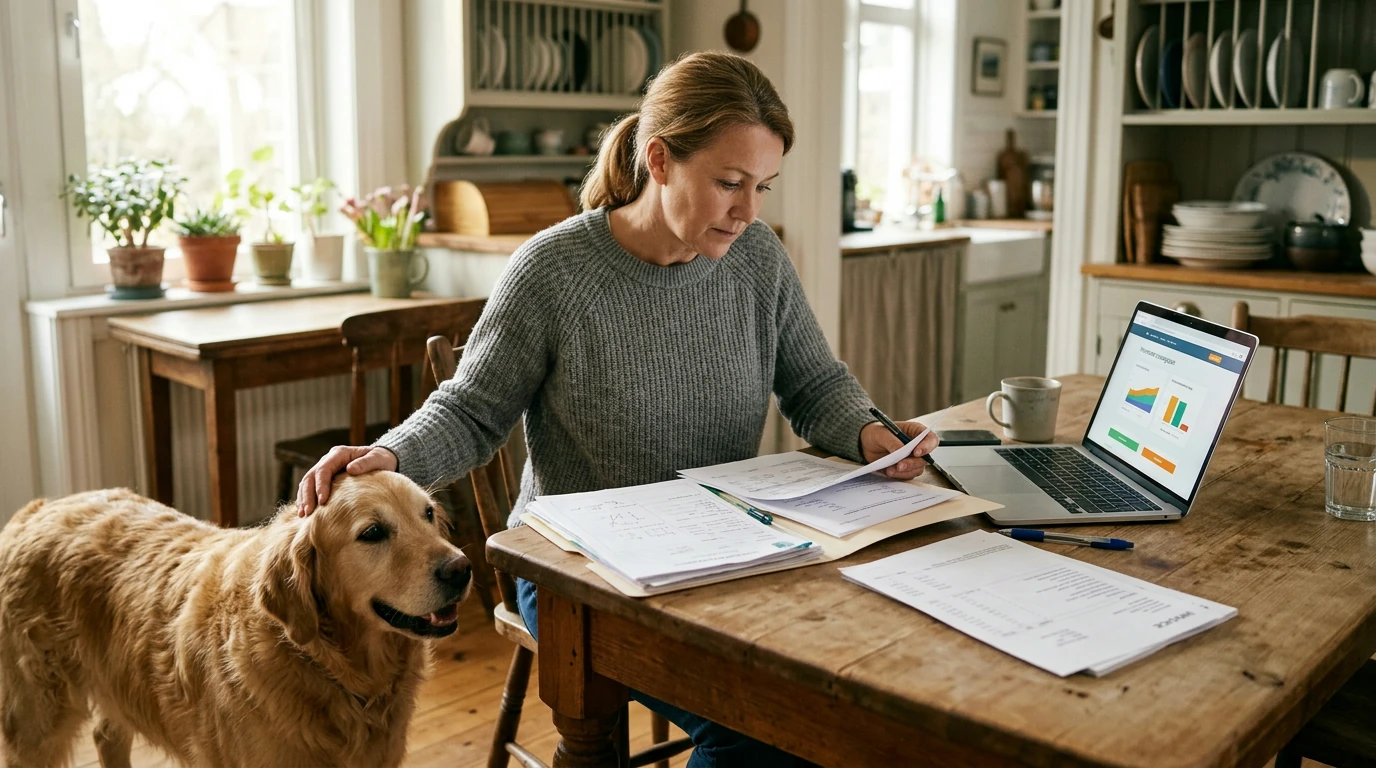
The easiest claim is the one you prepared for before the stressful day arrives. A simple routine can prevent missing records and reduce back-and-forth on pre-existing questions.
- Keep a simple medical timeline: adoption date, vaccines, routine visits, prior diagnoses, meds, lab results.
- Save itemized invoices (line-by-line charges), not just the payment total.
- Ask for complete records: SOAP notes, discharge summaries, diagnostic results, treatment plans.
- Document when symptoms started; a clear symptom timeline often matters.
- Know the insurer’s documentation checklist: claim form, vet notes, proof of payment (if required).
How to file a cleaner pet insurance claim (and avoid common delays)
Using AI-driven decision tools without giving up control
AI tools are most useful when you treat them like structured checklists and calculators—not as the final authority. You stay accountable for decisions, and the insurer’s contract language stays the source of truth. For broader consumer guidance, you can also review resources from the NAIC, pet-care education from the AVMA, and best practices for responsible AI use from the FTC.
What to prioritize when picking coverage for your pet’s stage of life
A simple workflow to make better insurance decisions faster
Put the full system in one place
If you want a structured, step-by-step framework you can use during real vet situations, our team recommends keeping a dedicated quick-reference guide with your policy documents. That’s exactly what Pet Protection Made Simple: Your Ultimate Guide to Pet Insurance, Claims, and AI-Driven Decisions is built for—so you can move from “What do we do now?” to a clean submission plan in minutes.
To make the routine stick, it helps to keep your paperwork physically and digitally organized. Some customers also pair their claim folder with a durable carry option like our Waterproof Anti-Theft Laptop Backpack with USB Charging Port – Fits 15.6″ Laptop for travel days, and a writing/communication refresher like Creative Writing Exercises eBook when they want help drafting a clear symptom timeline or a concise appeal letter that matches the insurer’s questions.
FAQ
What documents are usually needed for a pet insurance claim?
Most claims require a completed claim form, an itemized invoice, and your pet’s relevant medical records (often including vet notes). If diagnostics were performed, lab results or imaging reports are commonly needed, and some insurers also request proof of payment.
How can AI help with pet insurance decisions without making the choice for you?
AI can organize policy terms into a simple comparison, run reimbursement scenarios, and highlight missing claim components before you submit. You still confirm the results against your actual policy language and any instructions from the insurer.
Why do pet insurance claims get denied for pre-existing conditions?
Denials often hinge on when symptoms first appeared, what prior vet notes say, and how the policy defines “pre-existing,” including waiting periods. If you disagree, you can request the EOB and submit clarifying records that document symptom onset and clinical context.



Leave a comment